The problem isn't the grant. It's that nobody stays.
is the ecosystem that makes CSR capital actually work — turning one-time grants into formal credit, savings habits, insurance cover and a credit history that lasts.
Grants end at disbursement. We are what comes after.
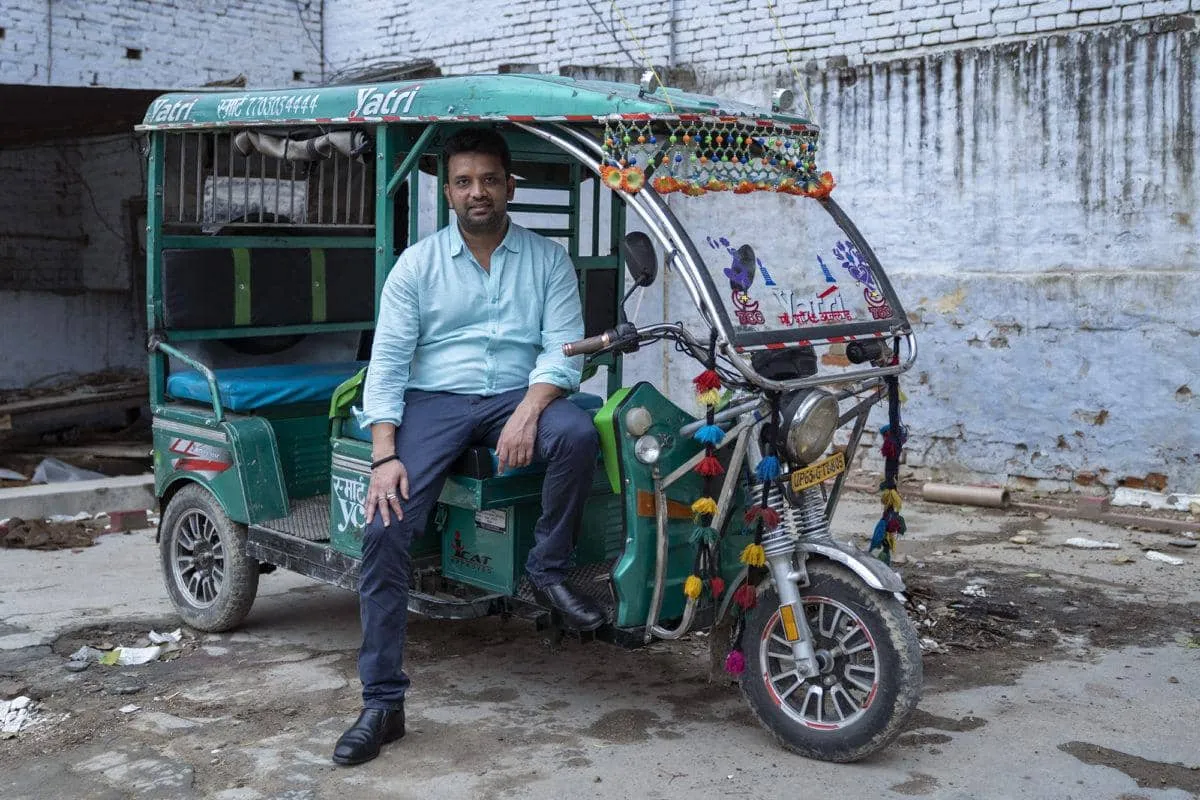
India's financial-inclusion gap is not a money problem — it's a follow-through problem. The credit-invisible get declined by lenders, and the grants they do receive end at disbursement: no hand-holding, no follow-up, no one to make sure the money actually changes a life.
The ₹100 story — what one rupee of CSR capital actually becomes.
Hand-holding for years, not days. The same money keeps financing new livelihoods — zero new CSR.
The Split
₹100 of CSR capital divides in two: ₹50 upfront subsidy that halves the price to finance, ₹50 credit-guarantee pool as first-loss cover for the lender.
customizable per programmeThe Crowd-in
The ₹50 guarantee unlocks a ₹50 NBFC loan — ₹100 of livelihood assets deployed, half of it institutional capital a grant alone never reaches.
grant doubles itselfThe Tenure
Earnings auto-split as they arrive: EMI to the lender, savings to the household, insurance to cover, investment to the future. Every repayment builds the credit file the person never had.
credit from day oneThe Recycle
The pool absorbs the 10% defaults, on-time members earn rewards, and the balance plows into the next cohort. The same ₹100 keeps financing new livelihoods.
zero new CSRFunds move directly between the parties. never holds or collects money.
More impact from every rupee invested.
Illustrative mechanics — scales to any corpus size. Modelled projection; to be validated with real programme data.
Be the first to see the engine run.
We are onboarding a first cohort of CSR funders, NGOs and lenders. Reach out for an early walkthrough and a fit assessment for your programme.